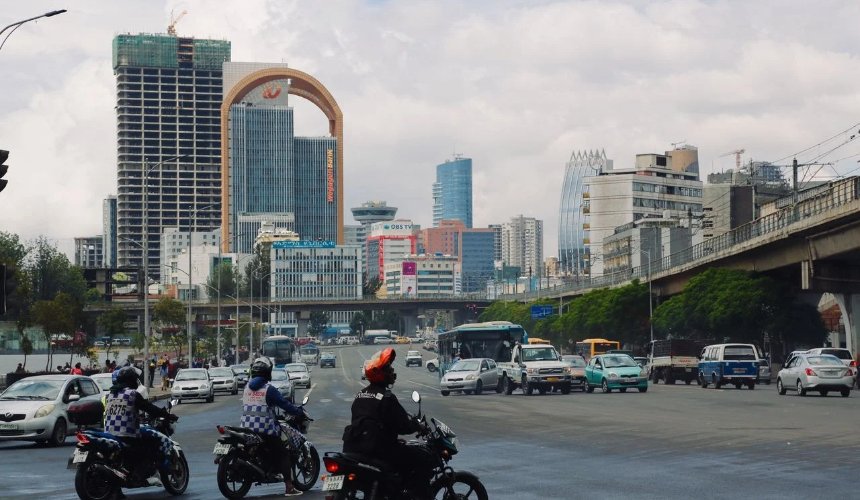

ADDIS ABABA
Sub-Saharan Africa is heading into 2027 with growth holding steady despite higher energy and food prices, climate shocks and uneven access to external financing.
The region’s economy is projected to expand 4.5% in both 2026 and 2027, according to the International Monetary Fund’s October World Economic Outlook (WEO). That compares with global growth of 3.1% this year and 3.4% next year.
The IMF says that stability masks substantial divergence across countries, reflecting differences in policy space, reform implementation, commodity exposure, climate shocks and access to external financing.
Oil-importing, non-resource-intensive economies are more exposed to higher energy and food prices, while some larger economies continue to benefit from earlier stabilization and reform efforts.
That divergence is visible among the region’s biggest economies. Nigeria is forecast to grow 4.2% in 2026 and 4.3% in 2027, while South Africa is projected to expand just 1% this year and 1.3% next year. Oil exporters as a group are expected to grow 4.2% in 2026 before easing slightly to 4.1% in 2027.
Some of the strongest numbers are farther east
Ethiopia’s economy is projected to grow 9.2% in 2026, matching the IMF’s estimate for 2025, before slowing to 7.8% in 2027.
Rwanda is forecast to expand 7.4% this year and 7.2% next year, while South Sudan, after an estimated 41.4% rebound in 2025, is projected to grow 10.5% in 2026 before slowing sharply to 3.9% in 2027. The Rwanda and South Sudan projections are reported in the WEO’s sub-Saharan Africa table.
Ethiopia’s growth also comes with persistent price pressures, with average consumer inflation projected at 11.7% in 2026 and 12.3% in 2027. Its current-account deficit is expected to widen to 2.5% of gross domestic product this year before narrowing to 1.3% in 2027.
Beyond the country forecasts, higher food and energy prices can widen current-account deficits in importing countries, increase external financing needs and put pressure on currencies, while low-income economies often have limited fiscal and external buffers.
Declining official development assistance can leave fewer resources available to cushion shocks and finance development needs.
Food prices remain a particular vulnerability
Extreme weather, transport disruptions and higher fertilizer costs can push food prices higher, with lower-income households especially exposed because basic necessities account for a larger share of their spending.
The IMF’s analysis finds that cost-of-living crises impose heavier burdens on poorer households, while persistent increases in the prices of basic necessities can erode real wages, weigh on domestic demand and worsen poverty outcomes.
The WEO also points to a stronger sovereign-bank nexus across emerging and developing economies.
Greater bank holdings of government securities are associated with lower lending to the private sector, particularly in high-debt emerging markets and low-income countries, potentially weakening domestic investment and reinforcing fiscal vulnerabilities.
That makes the design of fiscal support more consequential, with the IMF’s analysis finding that targeted transfers can protect vulnerable households while preserving price signals and requiring substantially fewer fiscal resources than broad price-suppressing measures.
In one simulation involving low-income developing countries facing a food-price shock, targeted transfers delivered a similar improvement in consumption for poorer households at roughly one-sixth of the fiscal cost of consumer subsidies.
The chapter also finds that stronger social-protection systems can make targeted support more effective and preserve fiscal space for future crises.